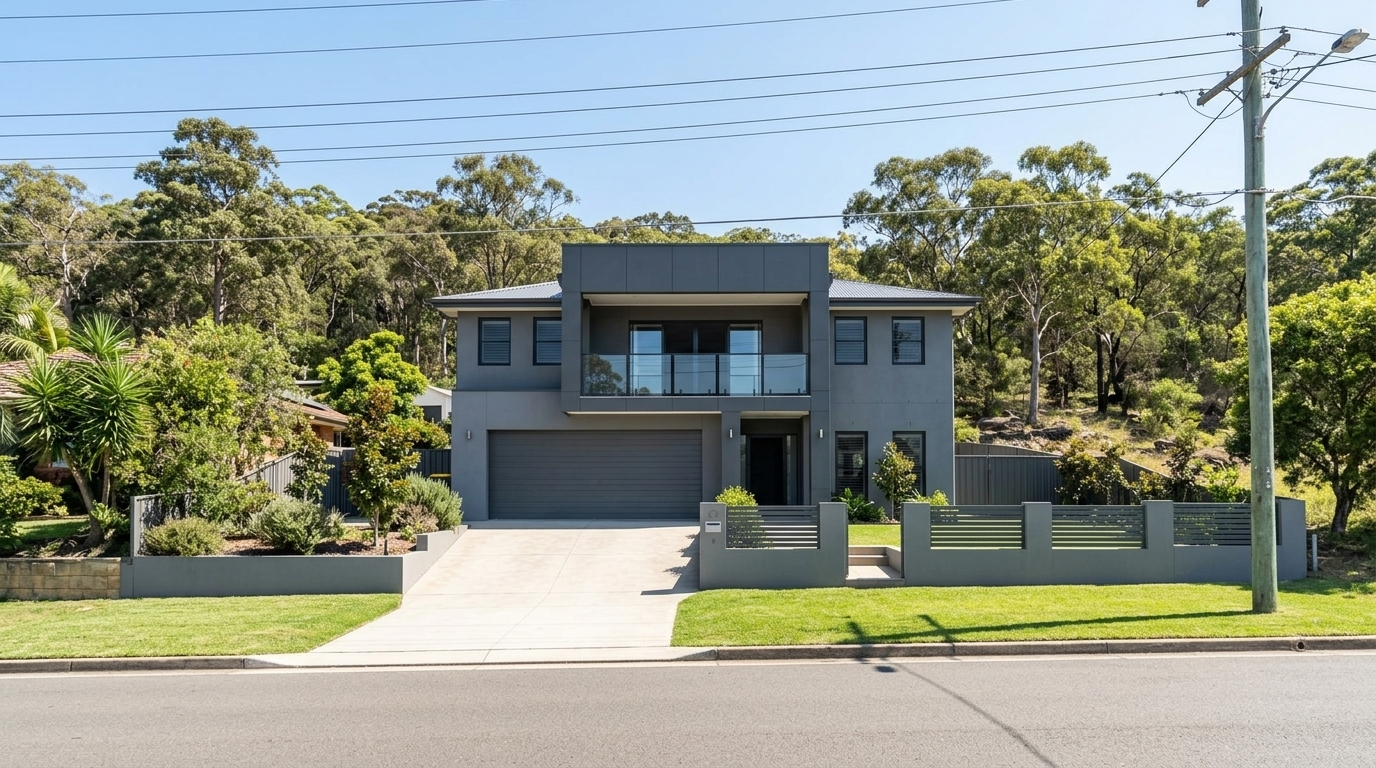
Blackwall’s property landscape spans a genuine spread: entry-level townhouses in the high $500,000s, family homes around the million-dollar mark, and multimillion-dollar waterfront residences along Orange Grove Road. That means lender’s mortgage insurance, the additional cost triggered when your deposit falls short of 20%, affects Blackwall buyers in sharply different ways depending on where they sit on the price ladder.
With a median house listing price around $1.25 million, the 20% deposit hurdle here is roughly $250,000. Blackwall’s median weekly household income is $1,449. This guide walks through exactly when LMI kicks in, what it costs at actual Blackwall property values, and the pathways available to reduce or eliminate it.
What Is Lender’s Mortgage Insurance?
Lender’s mortgage insurance is a one-off, non-refundable premium that protects the lender, not you, if you default on your home loan. It is typically required when your deposit is less than 20% of the property’s value, meaning your loan-to-value ratio (LVR) sits above 80%.
Many first home buyers focus on stamp duty as the main upfront cost and are caught off guard by LMI. It can add from roughly $17,000 on an entry-level Blackwall unit to over $50,000 on a mid-range house. LMI is distinct from mortgage protection insurance or income protection. It does not cover your repayments if you fall ill or lose your job. It exists solely to reduce the lender’s risk. Premiums can differ by thousands of dollars between insurers for the same loan, which is why using a mortgage broker who compares across lenders matters.
LMI at Blackwall Price Points: Real Numbers
Here is what LMI looks like at three real Blackwall price points, based on recent NSW Valuer General sales data and Money.com.au’s LMI tables.
Scenario A: Entry-level unit at $700,000
Blackwall units and townhouses have sold recently in the $570,000 to $760,000 range. A $700,000 purchase, like 2/22 Warwick Street (which sold for that figure in December 2025), is a realistic entry point.
- 20% deposit ($140,000): LMI = $0
- 15% deposit ($105,000): LMI ≈ $17,350
- 10% deposit ($70,000): LMI ≈ $26,740
- 5% deposit ($35,000): LMI ≈ $30,797
Scenario B: Entry-level house at $950,000
Entry-level houses start around the mid-$900,000s. 48 Warwick Street sold for $950,000 in April 2026.
- 20% deposit ($190,000): LMI = $0
- 15% deposit ($142,500): LMI ≈ $29,000 to $31,000
- 10% deposit ($95,000): LMI ≈ $38,000 to $40,000
- 5% deposit ($47,500): LMI ≈ $42,000 to $44,000
Scenario C: Mid-range house or larger townhouse at $1,200,000
A townhouse at 5/48 Gallipoli Avenue sold for $1,200,000 in April 2026.
- 20% deposit ($240,000): LMI = $0
- 10% deposit ($120,000): LMI ≈ $48,000 to $50,000
- 5% deposit ($60,000): LMI ≈ $53,000+
With Blackwall’s median household income at $1,449 per week, saving a 20% deposit on even the entry-level house ($190,000) represents a multi-year commitment for most local households.
When Does LMI Apply? The Full Picture
The basic rule: deposit under 20%, LMI generally applies. But several other situations can trigger it.
Investor loans attract higher premiums. According to the Helia fee estimator, LMI on investment properties is higher than on owner-occupied loans. This matters in Blackwall, where 25.75% of households rent and median weekly rent for houses is $650.
Refinancing below 80% LVR means paying LMI again. LMI is not transferable between lenders. Building equity through extra repayments or home improvements before refinancing helps avoid a second charge.
Some lenders charge LMI below 80% LVR. Depending on their internal risk assessment, lenders may require LMI even when your deposit exceeds 20%, particularly if your credit profile, employment type, or savings history does not meet their criteria.
Pathways Around LMI: What Blackwall Buyers Can Use in 2026
Several mechanisms exist to reduce or avoid LMI, and many are accessible to Blackwall buyers right now.
The Federal 5% Deposit Scheme. From October 2025, the Australian Government’s scheme expanded with no income caps and unlimited places. Buy with as little as a 5% deposit and no LMI; the government guarantees up to 15% of the loan. Confirm the property price cap for Blackwall (2256) with a participating lender. Over 260,000 Australians have used the scheme since 2022.
NSW First Home Buyers Assistance Scheme. Stamp duty relief does not directly remove LMI, but it frees up cash for a larger deposit. Under the NSW scheme, eligible buyers receive a full exemption on homes up to $800,000 and a reduced rate up to $1,000,000. A $760,000 Blackwall unit, such as 2/10 Wallaby Street (April 2026), qualifies for the full exemption, saving over $30,000. For the 2026/27 financial year, reduced duty on an $850,000 home is $9,796.75, scaling to $37,227.65 at $990,000.
Professional LMI Waivers. Many lenders waive LMI up to 90% to 95% LVR for doctors, dentists, pharmacists, lawyers, accountants, nurses, teachers, police, firefighters, engineers, and veterinarians. In June 2026, Bankwest expanded waivers to major tech company employees and some federal government roles. Blackwall’s most common occupations are Professional and Trades, so a meaningful share of local buyers may qualify.
Help to Buy Shared Equity Scheme. The federal Help to Buy scheme lets eligible buyers purchase with a 2% deposit, with the government contributing up to 30% equity for existing homes or 40% for new builds, keeping your LVR low enough to avoid LMI. Income caps of $103,000 for singles and $165,000 for couples and single parents apply. The scheme is available on the Central Coast as a regional NSW area. It is particularly relevant for Blackwall buyers who can service a loan but are saving against rising rents, according to Shoreline Lending. Confirm Blackwall’s property price cap with a participating lender.
Guarantor Loans. A family guarantor uses equity in their property to cover the deposit shortfall, allowing borrowing up to 105% of the purchase price without LMI. The guarantor takes partial responsibility for the debt until released.
First Home Owner Grant. The FHOG provides $10,000 toward new or substantially renovated homes ($600,000 cap for new dwellings, $750,000 for house-and-land). While Blackwall is largely established, nearby Central Coast growth corridors offer new-build opportunities within these caps.
Should You Pay LMI or Save Longer? A Blackwall Perspective
Blackwall’s 10-year average annual house price growth sits at 8.7%, according to WhichAgent data. In a market growing at that pace, the 20% deposit target is a moving one: if you spend a year saving an extra $50,000 while prices rise 8.7%, a $950,000 home becomes roughly $1,032,000, and the 20% threshold moves from $190,000 to $206,400. The gap widens, not narrows.
There is also the question of how you pay. Adding a $26,305 LMI premium to a $570,000 loan at 6.00% over 30 years costs roughly $56,776 in extra interest. Paying upfront avoids that, but most borrowers add it to the loan to preserve cash at settlement. For many Blackwall buyers planning to hold long-term in a suburb with strong waterfront appeal, entering sooner with LMI can be the sounder choice.
Practical Next Steps for Blackwall Buyers
Start by speaking with a mortgage broker who understands the Central Coast market. Brokers can compare LMI premiums across multiple lenders; the difference can run to thousands for the same loan. Check your eligibility for the 5% Deposit Scheme, NSW stamp duty relief, and any professional LMI waiver. Get pre-approval to understand your borrowing capacity with and without LMI.
Local brokerages like Wisebuy Home Loans and Central Coast Mortgages know the Blackwall, Woy Woy, and Ettalong Beach market and can model both scenarios with real numbers.
Frequently Asked Questions
How much does lender’s mortgage insurance cost on a typical Blackwall property?
On a $700,000 Blackwall unit with a 10% deposit, LMI costs approximately $26,740. On a $950,000 Blackwall house with a 10% deposit, expect roughly $38,000 to $40,000. Premiums vary by lender and insurer, so speaking with a mortgage broker who compares across multiple lenders is the best way to get an accurate quote.
What exactly is lender’s mortgage insurance and who does it protect when buying in Blackwall?
LMI protects the lender against borrower default. It does not protect you, your family, or your repayments. It is a one-off, non-refundable premium paid at settlement and is entirely separate from mortgage protection insurance, income protection, or life insurance. If you buy in Blackwall with less than a 20% deposit, the lender will almost certainly require it.
At what deposit size does LMI apply when buying in Blackwall?
LMI generally applies when your deposit is less than 20% of the property’s value, meaning your LVR exceeds 80%. The smaller the deposit, the higher the premium. Some lenders may also charge LMI at lower LVRs depending on their internal risk assessment.
Does the federal 5% Deposit Scheme mean I can buy in Blackwall without paying LMI?
Yes. From October 2025, eligible first home buyers can purchase with a 5% deposit and no LMI under the expanded scheme, which now has no income caps and unlimited places. Property price caps still apply, so confirm the cap for Blackwall (2256) with a participating lender.
Can I avoid LMI through the NSW stamp duty concessions when buying in Blackwall?
Not directly: stamp duty relief and LMI are separate costs. However, saving on stamp duty frees up money for a larger deposit, which could push you over the 20% threshold. A $760,000 unit in Blackwall qualifies for the full stamp duty exemption, saving more than $30,000 that can be redirected into your deposit.
What professions qualify for an LMI waiver for a Blackwall home loan?
Doctors, dentists, pharmacists, lawyers, accountants, nurses, teachers, police, firefighters, engineers, and veterinarians typically qualify. In June 2026, Bankwest expanded waivers to major tech company employees and some federal government roles. Policies vary by lender, so confirm eligibility before relying on a waiver for your Blackwall purchase.
If I refinance my Blackwall home, will I have to pay LMI again?
Yes, if you refinance with less than 20% equity, LMI is not transferable between lenders. Building equity through extra repayments or home improvements before refinancing can help you avoid a second LMI charge.
Is it better to pay LMI upfront or add it to the home loan for a Blackwall property?
Paying upfront is cheaper. Adding a $26,305 LMI premium to a $570,000 loan at 6.00% over 30 years costs roughly $56,776 in extra interest. That said, most borrowers in Blackwall add LMI to the loan to preserve cash at settlement, which is reasonable if it gets you into the market sooner.
Can a guarantor help me avoid LMI on a Blackwall purchase?
Yes. A family guarantor can use equity in their property to cover the deposit shortfall, allowing you to borrow up to 105% of the Blackwall purchase price without LMI. The guarantor takes partial responsibility for the debt and a caveat may be placed on their property until released.
With Blackwall house prices around $1.25 million, what deposit do I need to avoid LMI?
You would need 20%, roughly $250,000. Against Blackwall’s median household income of $1,449 per week, that is a significant sum. This is why government schemes, professional waivers, and guarantor loans are so relevant for local buyers.
Does the Help to Buy shared equity scheme work for Blackwall properties?
Yes, provided you meet the criteria. Help to Buy lets you purchase with a 2% deposit, with the government contributing up to 30% equity for existing homes or 40% for new builds, keeping your LVR low enough to avoid LMI. Income caps apply ($103,000 for singles, $165,000 for couples and single parents), and property price caps apply by location. Confirm Blackwall’s cap with a participating lender.
Should I pay LMI and buy now in Blackwall, or keep saving for a 20% deposit?
With Blackwall’s 10-year average annual house price growth of 8.7%, waiting can mean the 20% target keeps pulling away. If you can comfortably afford the repayments and plan to hold long-term, entering sooner with LMI can be a sound strategy. A mortgage broker who knows the Central Coast market can model both paths with real numbers.